Debt Consolidation in 2026: Top Strategies to Lower Payments
Anúncios
Debt Consolidation in 2026: Comparing 3 Top Strategies to Lower Your Monthly Payments by Up to 20%
Are you feeling overwhelmed by multiple high-interest debts? The thought of juggling various due dates and minimum payments can be daunting, leading to stress and hindering your financial progress. If you’re looking for a strategic way to simplify your finances, reduce your interest burden, and potentially lower your monthly payments by a significant margin, then understanding effective debt consolidation strategies is crucial, especially as we navigate the financial landscape of 2026.
Anúncios
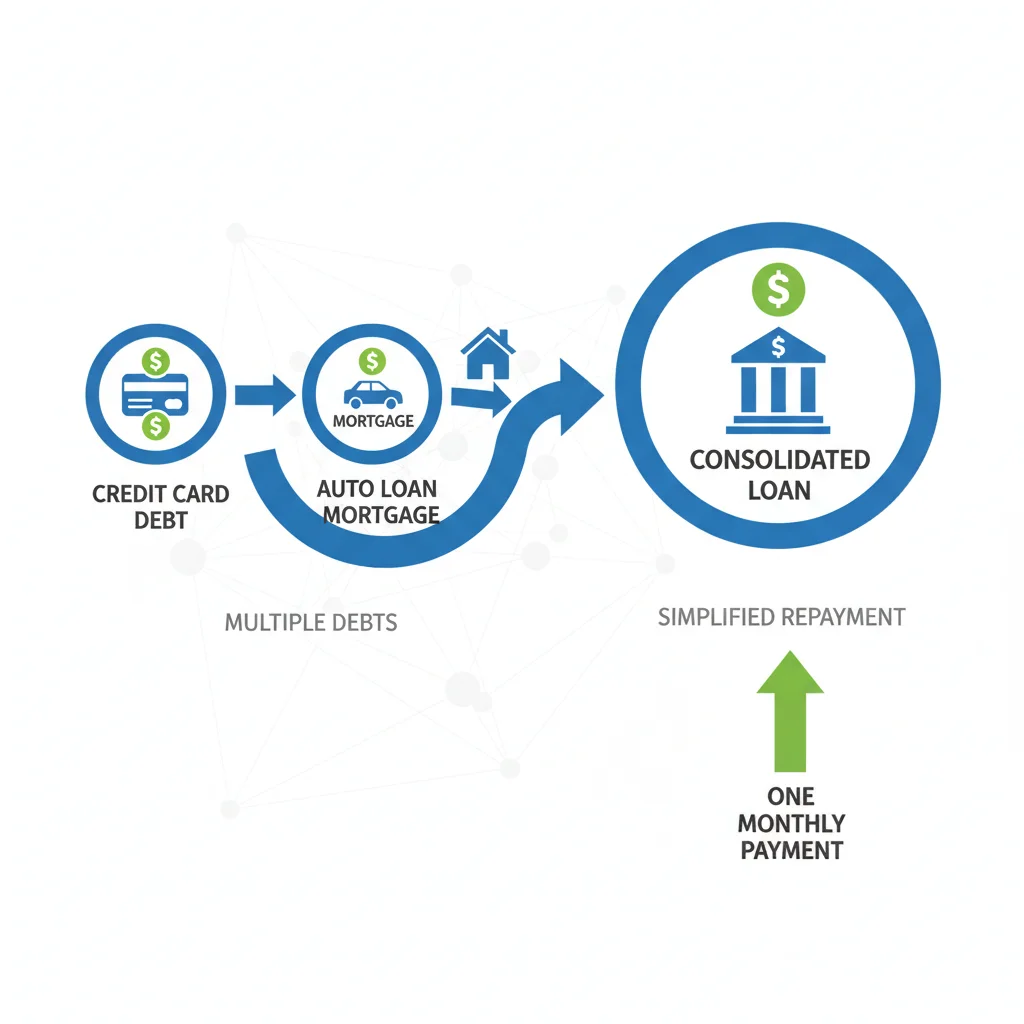
Debt consolidation isn’t just about combining debts; it’s a powerful financial tool designed to streamline your repayment process, often resulting in a single, more manageable monthly payment with a lower interest rate. This can free up cash flow, accelerate your debt repayment journey, and provide a much-needed sense of control over your financial future. In this comprehensive guide, we’ll delve into the top three debt consolidation strategies for 2026, comparing their benefits, drawbacks, and who they are best suited for. Our goal is to equip you with the knowledge to make an informed decision that could potentially lower your monthly payments by up to 20% or even more.
Understanding the Core Principle of Debt Consolidation
Before we dive into specific methods, let’s solidify our understanding of what debt consolidation truly entails. At its heart, debt consolidation involves taking out a new loan or line of credit to pay off several existing debts. Instead of making multiple payments to different creditors, you make one single payment to the new lender. The primary advantages typically include:
- Simplified Payments: One payment, one due date, less stress.
- Lower Interest Rates: Often, the new consolidated loan has a lower interest rate than your combined existing debts, saving you money over time.
- Reduced Monthly Payments: A lower interest rate and/or a longer repayment term can significantly decrease your monthly financial outflow.
- Improved Credit Score (Potentially): By consistently making on-time payments on your consolidated debt, you can positively impact your credit score.
However, it’s not a magic bullet. It requires discipline and a commitment to not accumulating new debt. The success of any debt consolidation strategy hinges on careful planning and execution.
Anúncios
Strategy 1: Balance Transfer Credit Cards – A Short-Term Solution for High-Interest Debt
Balance transfer credit cards remain a popular and often effective debt consolidation strategy for individuals with good to excellent credit who want to tackle high-interest credit card debt. The appeal lies in their introductory 0% APR periods.
How Balance Transfer Credit Cards Work
With a balance transfer card, you apply for a new credit card that offers a promotional 0% introductory Annual Percentage Rate (APR) on transferred balances for a specific period, typically ranging from 6 to 21 months. You then transfer your existing high-interest credit card balances to this new card. During the introductory period, all your payments go directly towards the principal, allowing you to pay down your debt much faster without accruing interest.
Benefits:
- 0% Interest Period: This is the biggest draw. You can pay down a substantial amount of principal without interest charges, leading to significant savings.
- Simplified Payments: All transferred balances are consolidated into one monthly payment on the new card.
- Potential for Quick Debt Elimination: If you can pay off the transferred balance before the promotional period ends, you effectively pay zero interest on that debt.
Drawbacks:
- Balance Transfer Fees: Most cards charge a balance transfer fee, usually 3% to 5% of the transferred amount. While this adds to the debt, it’s often less than the interest you’d pay otherwise.
- Introductory Period Expiration: If you don’t pay off the balance before the 0% APR period ends, the remaining balance will be subject to the card’s standard (often high) APR.
- Credit Score Requirement: You generally need a good to excellent credit score (typically 670+) to qualify for the best balance transfer offers.
- Credit Limit Restrictions: The new card’s credit limit might not be high enough to consolidate all your existing debt.
Who is it Best For?
This debt consolidation strategy is ideal for individuals with:
- A strong credit score.
- A clear plan to pay off the transferred balance before the 0% APR period expires.
- Manageable debt amounts that can fit within a typical balance transfer credit limit.
Example in 2026: Sarah has $10,000 in credit card debt across three cards, with an average APR of 20%. She qualifies for a balance transfer card with a 0% APR for 18 months and a 3% transfer fee. She transfers the $10,000, incurring a $300 fee. If she pays $572.22 per month, she’ll pay off the entire $10,300 before the 18 months are up, saving thousands in interest compared to her previous cards.
Strategy 2: Personal Loans – A Flexible Option for Various Debts
Personal loans are another highly effective debt consolidation strategy, particularly for those with diverse types of debt, including credit cards, medical bills, or even smaller personal loans.
How Personal Loans Work
A personal loan is an unsecured loan (meaning it doesn’t require collateral) that you receive as a lump sum. You use this lump sum to pay off your existing debts. You then repay the personal loan with fixed monthly payments over a set period, typically 2 to 7 years, at a fixed interest rate. This predictability is a major advantage.
Benefits:
- Fixed Interest Rate and Payments: You know exactly how much you’ll pay each month and for how long, making budgeting easier.
- Lower Interest Rates: If your credit score is good, you can often secure a personal loan with a much lower interest rate than high-interest credit cards.
- Consolidate Various Debt Types: Unlike balance transfer cards, personal loans can be used to consolidate almost any type of unsecured debt.
- Predictable Repayment Schedule: The fixed term provides a clear end date for your debt.
Drawbacks:
- Credit Score Dependent: The best rates are reserved for those with excellent credit. If your credit is fair or poor, the interest rate might not be significantly lower than your existing debts, or you might not qualify at all.
- Origination Fees: Some lenders charge an origination fee, typically 1% to 8% of the loan amount, which is deducted from the loan proceeds.
- Longer Repayment Terms: While lower monthly payments are attractive, a longer repayment term means you’ll pay more interest over the life of the loan if the interest rate isn’t substantially lower.
Who is it Best For?
This debt consolidation strategy is suitable for individuals with:
- A good to excellent credit score.
- A combination of different high-interest debts.
- A preference for predictable, fixed monthly payments.
- A need to consolidate a larger amount of debt than a balance transfer card might allow.
Example in 2026: Mark has $15,000 in various debts (credit cards, an old medical bill) with an average interest rate of 18%. He secures a 5-year personal loan for $15,000 at a 9% APR. His new monthly payment is $311.38. Compared to his previous payments totaling $450 with fluctuating interest, he saves $138.62 per month and will pay off his debt in a fixed timeframe, saving thousands in interest over the loan’s life.
Strategy 3: Debt Management Plans (DMPs) – Structured Support for Challenging Debt
For those struggling with significant credit card debt and perhaps a less-than-perfect credit score, a Debt Management Plan (DMP) offered by a credit counseling agency can be an invaluable debt consolidation strategy.
How Debt Management Plans Work
A DMP is facilitated by a non-profit credit counseling agency. You work with a certified credit counselor who assesses your financial situation and helps you create a budget. The counselor then negotiates with your creditors on your behalf to potentially lower your interest rates, waive fees, and reduce your monthly payments. Instead of paying individual creditors, you make one consolidated monthly payment to the credit counseling agency, which then distributes the funds to your creditors. DMPs typically last 3 to 5 years.
Benefits:
- Lower Interest Rates: Creditors are often willing to reduce interest rates significantly for consumers on a DMP, as they prefer to receive some payment rather than none.
- Waived Fees: Late fees and over-limit fees can often be waived.
- Simplified Payments: One predictable monthly payment to the agency.
- Credit Counseling and Education: You receive guidance on budgeting and financial management, helping you avoid future debt problems.
- Accessible for Lower Credit Scores: Unlike balance transfer cards or personal loans, a DMP is often an option even if your credit score is not ideal.
- Stopping Collection Calls: Once enrolled, collection calls usually cease.
Drawbacks:
- Impact on Credit Score: While you’re on a DMP, your credit report might show that you are in a debt management program, which can negatively impact your score in the short term. However, consistent on-time payments within the plan can improve it over time.
- Restrictions: You typically cannot open new credit accounts while on a DMP.
- Fees: While non-profit agencies are the norm, some may charge a small monthly fee for their services.
- Not All Debts Included: DMPs primarily focus on unsecured debts like credit cards. Mortgages, car loans, and student loans are usually not included.
Who is it Best For?
This debt consolidation strategy is most suitable for individuals who:
- Are struggling with a substantial amount of unsecured debt, primarily credit cards.
- Have a lower credit score that prevents them from qualifying for balance transfer cards or personal loans at favorable rates.
- Need structured support and guidance to manage their finances and repay debt.
- Are committed to a disciplined repayment plan and avoiding new debt.
Example in 2026: Lisa has $20,000 in credit card debt with an average APR of 25%. Her minimum payments total $800, which she struggles to meet. She enrolls in a DMP. Her credit counselor negotiates her interest rates down to an average of 10% and waives some fees. Her new consolidated monthly payment is $450, allowing her to manage her finances and pay off her debt in 4 years, saving significant interest and avoiding bankruptcy.
Choosing the Right Debt Consolidation Strategy for You
Selecting the best debt consolidation strategy depends heavily on your individual financial situation, credit score, and debt profile. Here’s a quick comparison to help you decide:
- Good to Excellent Credit (670+ FICO Score) & Manageable Credit Card Debt: A balance transfer credit card could be your best bet, especially if you can pay it off during the 0% APR period.
- Good to Excellent Credit (670+ FICO Score) & Diverse Debts/Larger Amounts: A personal loan offers fixed payments and lower interest rates for a variety of unsecured debts.
- Fair to Poor Credit (Below 670 FICO Score) & Significant Credit Card Debt: A Debt Management Plan provides structured support, lower interest rates, and financial guidance, even with a less-than-perfect credit history.
It’s crucial to assess your current financial health before making a decision. Consider factors such as:
- Your Credit Score: This will largely determine your eligibility and the interest rates you’re offered.
- Total Debt Amount: Some strategies are better suited for smaller or larger debt loads.
- Types of Debt: Are you consolidating only credit cards, or a mix of various unsecured debts?
- Your Discipline: Are you confident you can stick to a repayment plan and avoid accumulating new debt?
Beyond Consolidation: Essential Tips for Long-Term Financial Health
While debt consolidation strategies are excellent tools for immediate relief, true financial freedom comes from adopting sustainable money habits. Here are some additional tips for 2026 and beyond:
1. Create and Stick to a Realistic Budget
A budget is your financial roadmap. It helps you understand where your money is going and identify areas where you can cut back. Regularly review and adjust your budget to ensure it aligns with your income and expenses. This is fundamental to preventing future debt accumulation.
2. Build an Emergency Fund
Life is unpredictable. An emergency fund – ideally 3 to 6 months’ worth of living expenses – can protect you from falling back into debt when unexpected costs arise, such as medical emergencies or job loss. Start small and contribute regularly.
3. Avoid New Debt
The most critical component of any successful debt consolidation strategy is to stop accumulating new debt. Cut up credit cards if necessary, and resist the temptation to make impulse purchases. Live within your means.
4. Monitor Your Credit Report Regularly
Keep an eye on your credit report for errors and to track your progress. You can get a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once every 12 months at AnnualCreditReport.com.
5. Seek Professional Advice When Needed
If you’re unsure which debt consolidation strategy is right for you, or if you continue to struggle with debt, don’t hesitate to seek advice from a financial advisor or a certified credit counselor. They can provide personalized guidance and help you navigate complex financial situations.
The Future of Debt Consolidation in 2026
As we look to 2026, the financial landscape continues to evolve. Interest rates, while subject to change, remain a critical factor. Technological advancements are making it easier to compare loan offers and manage finances digitally. Online lenders are increasingly competitive, offering streamlined application processes for personal loans. Credit counseling agencies are also leveraging technology to provide more accessible and personalized support.
Understanding these trends can help you make an even more informed decision. Always compare offers from multiple lenders and agencies to ensure you’re getting the best terms available. The market for debt consolidation strategies is dynamic, and staying informed will empower you to secure the most advantageous solution for your unique needs.
Common Pitfalls to Avoid in Debt Consolidation
While debt consolidation offers a clear path to financial relief, it’s essential to be aware of potential pitfalls:
- Accumulating New Debt: This is arguably the biggest mistake. If you consolidate debt only to rack up new balances on your now-empty credit cards, you’ll end up in a worse position than when you started.
- Ignoring Fees: Always factor in balance transfer fees or origination fees. Sometimes, these can negate the benefits of a lower interest rate, especially for smaller debt amounts or shorter repayment periods.
- Not Understanding Terms: Read the fine print! Be clear on the interest rate, repayment term, any penalties for late payments, and what happens after a promotional APR period ends.
- Choosing the Wrong Strategy: As discussed, what works for one person may not work for another. Don’t jump into a solution without thoroughly evaluating if it aligns with your credit profile and financial goals.
- Falling for Scams: Be wary of companies promising unrealistic results or asking for large upfront fees. Stick with reputable lenders, banks, and non-profit credit counseling agencies.
Taking the First Step Towards Financial Freedom
Embarking on a debt consolidation strategy is a significant step towards taking control of your financial life. It requires diligence, research, and a commitment to change. By carefully evaluating balance transfer cards, personal loans, or debt management plans, you can find a solution that not only lowers your monthly payments but also sets you on a sustainable path to becoming debt-free.
Remember, the goal isn’t just to move debt around; it’s to eliminate it. With the right strategy and a renewed commitment to sound financial habits, you can achieve your goal of financial freedom in 2026 and beyond. Start by assessing your current debt, checking your credit score, and then exploring the options presented here. Your future self will thank you for making an informed decision today.