How to Build a Robust Emergency Fund: Your Guide to 6 Months of Living Expenses by December 2026
In an unpredictable world, financial stability isn’t just a luxury; it’s a necessity. One of the cornerstones of true financial security is a well-stocked emergency fund. This isn’t just about having some extra cash; it’s about creating a safety net that can catch you when life inevitably throws a curveball – whether it’s an unexpected job loss, a medical emergency, or a major home repair. Our ambitious yet entirely achievable goal? To help you accumulate six months’ worth of living expenses in your emergency fund by December 2026.
The journey to building a substantial emergency fund might seem daunting, especially if you’re starting from scratch or juggling other financial priorities. However, with a clear strategy, consistent effort, and a realistic timeline, this goal is well within your reach. This comprehensive guide will walk you through every step, from defining your target amount to implementing actionable saving strategies and maintaining your fund once it’s established. Let’s dive into how you can make your Emergency Fund 2026 a resounding success.
Anúncios
Understanding Your Emergency Fund: What It Is and Why It’s Crucial
Before we outline the ‘how,’ let’s solidify the ‘what’ and ‘why.’ An emergency fund is a stash of readily accessible cash specifically designated to cover unexpected expenses and financial disruptions. It’s not for a new car, a vacation, or a down payment on a house. It’s for emergencies – situations that are unforeseen and require immediate financial attention.
What Constitutes an Emergency Fund?
Think of your emergency fund as your personal financial airbag. It’s there to absorb the shock of unexpected events without forcing you into debt or derailing your long-term financial goals. Typically, financial experts recommend having three to six months’ worth of essential living expenses saved. For our purpose, we’re aiming for the higher end of that spectrum – a robust six months – to provide an even greater buffer against life’s uncertainties. This target makes your Emergency Fund 2026 goal truly impactful.
Anúncios
The Undeniable Benefits of a Solid Emergency Fund
- Peace of Mind: Knowing you have a financial cushion reduces stress and anxiety during difficult times.
- Debt Avoidance: Instead of relying on high-interest credit cards or loans, your emergency fund allows you to cover costs without incurring debt.
- Financial Freedom: It provides the flexibility to make decisions that are best for your long-term well-being, rather than being forced into choices due to immediate financial pressure.
- Opportunity: Sometimes, an emergency fund can even create opportunities, like allowing you to take a calculated risk in your career or move to a new city without immediate financial strain.
- Improved Credit Score: By avoiding new debt, you protect your credit score, which is crucial for future financial endeavors.
Building your Emergency Fund 2026 isn’t just about money; it’s about building resilience and security for yourself and your loved ones.
Step 1: Calculate Your Target – How Much Do You Really Need?
The first crucial step in building your Emergency Fund 2026 is to determine your specific target amount. This isn’t a one-size-fits-all number; it’s deeply personal and depends entirely on your current living expenses.
Identify Your Essential Monthly Expenses
Grab a pen and paper, or open a spreadsheet. It’s time to get brutally honest about where your money goes each month. Focus only on essential expenses – those costs you absolutely cannot avoid. These typically include:
- Housing: Rent or mortgage payments
- Utilities: Electricity, gas, water, internet (basic service)
- Food: Groceries (not dining out or gourmet items)
- Transportation: Car payment, insurance, fuel, public transport fares (to get to work/essential appointments)
- Insurance: Health, life, car (essential coverage)
- Minimum Debt Payments: Student loans, credit cards (only the minimum, not extra payments)
- Basic Communication: Cell phone plan
Exclude discretionary spending like entertainment, dining out, subscriptions you can live without, vacations, and non-essential shopping. The goal is to figure out the bare minimum you need to survive comfortably for a month.
Calculate Your Total Monthly Essentials
Add up all those essential expenses. Let’s say, for example, your essential monthly expenses come out to $2,500.
Set Your Six-Month Goal
Now, multiply your essential monthly total by six. Using our example:
$2,500 (Essential Monthly Expenses) x 6 Months = $15,000 (Your Emergency Fund Target)
This is the grand total you’re aiming for by December 2026. Write this number down. It’s your beacon for your Emergency Fund 2026 journey.
Step 2: Create a Realistic Timeline and Saving Plan
With your target amount in hand, the next step is to break it down into manageable, actionable chunks. December 2026 gives us a specific endpoint, which is excellent for planning.
Determine Your Timeframe
Let’s assume you’re starting today, in mid-2024. That gives you approximately 2.5 years, or roughly 30 months, until December 2026. This is a reasonable timeframe for many to build a substantial Emergency Fund 2026.
Calculate Your Monthly Saving Goal
Divide your total emergency fund target by the number of months you have until December 2026.
$15,000 (Target Fund) / 30 Months = $500 per month
So, in this example, you would need to save $500 each month to reach your Emergency Fund 2026 goal. Does this number feel achievable? If it seems too high, don’t despair. We’ll explore strategies to adjust your budget and boost your income shortly.
Set Up a Dedicated, Accessible Account
Your emergency fund should be kept separate from your everyday checking and savings accounts. This prevents you from accidentally spending it. Look for a high-yield savings account (HYSA) that offers a better interest rate than traditional savings accounts. This allows your money to grow, even if slowly, while remaining liquid. Ensure it’s easily accessible in an emergency, but not so easy that you’re tempted to dip into it for non-emergencies.
Step 3: Implement Aggressive Saving Strategies
Now for the core of building your Emergency Fund 2026: finding the money to save. This often involves a combination of cutting expenses and increasing income.
Budgeting: The Foundation of Saving
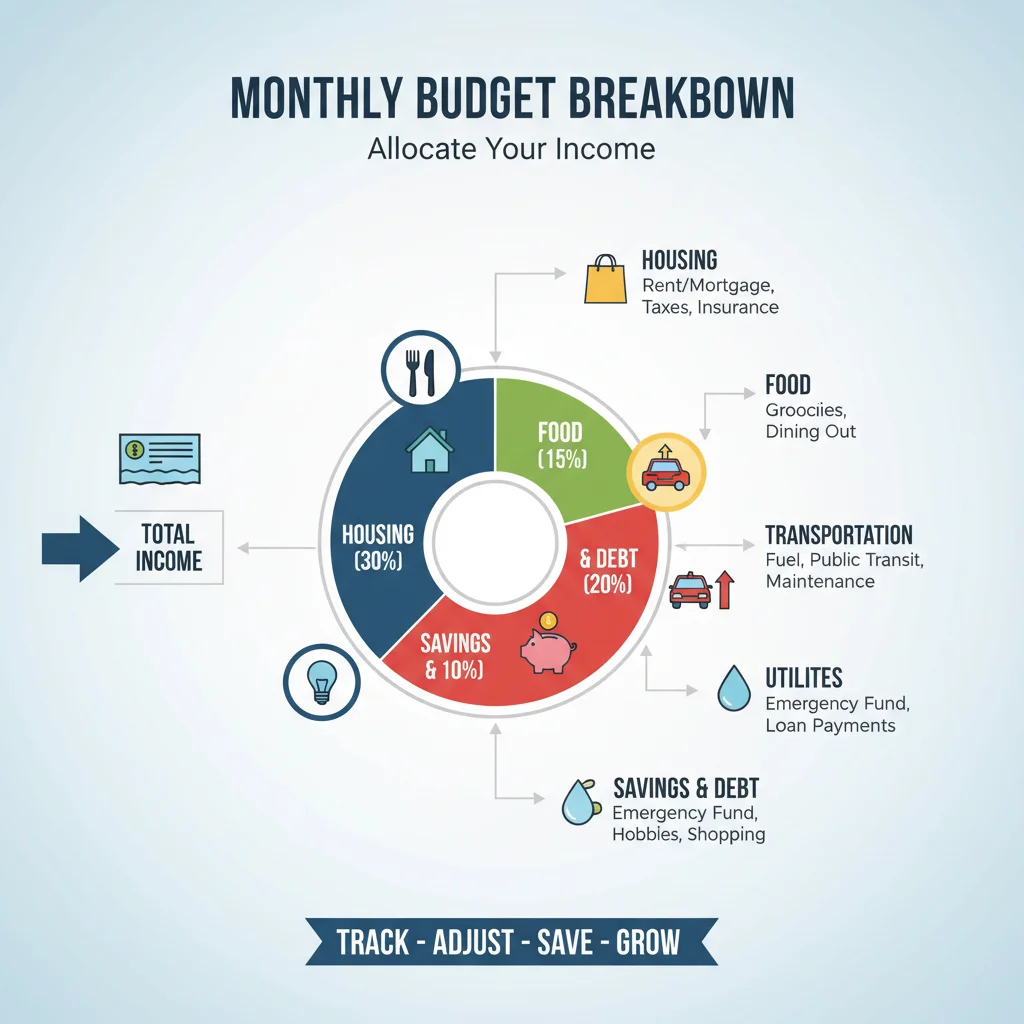
If you don’t already have one, create a detailed budget. This isn’t about restriction; it’s about awareness and control. Track every dollar you spend for at least a month to identify areas where you can cut back. Popular budgeting methods include:
- The 50/30/20 Rule: 50% needs, 30% wants, 20% savings/debt repayment. Aim to allocate a significant portion of that 20% (or even more) towards your emergency fund.
- Zero-Based Budgeting: Every dollar is assigned a job (saving, spending, debt). This ensures no money is left unaccounted for.
- Envelope System: For cash spenders, physically allocating cash into envelopes for different categories can be very effective.
Be ruthless in identifying non-essential spending. Can you cancel unused subscriptions? Reduce dining out? Cut down on impulse purchases? Every dollar saved is a dollar closer to your Emergency Fund 2026 goal.
Automate Your Savings
This is arguably the most powerful strategy. Set up an automatic transfer from your checking account to your dedicated emergency fund savings account on payday. Treat this transfer like any other bill – it’s non-negotiable. Out of sight, out of mind, and your fund will grow consistently without you having to actively think about it each month.
Boost Your Income (Even Temporarily)
If cutting expenses isn’t enough, or if you want to accelerate your progress, consider increasing your income. This doesn’t have to be a permanent change:
- Side Hustles: Freelance work, ride-sharing, food delivery, pet sitting, online tutoring – there are countless ways to earn extra cash.
- Sell Unused Items: Declutter your home and sell clothes, electronics, furniture, or collectibles you no longer need on platforms like eBay, Facebook Marketplace, or local consignment shops.
- Temporary Overtime: If your job offers it, pick up extra shifts or overtime hours.
- Negotiate a Raise: If you’re due for one, build your case and ask for an increase at your current job.
Direct every penny of this extra income straight into your Emergency Fund 2026. You’ll be surprised how quickly it adds up.
Leverage Windfalls and Bonuses
Did you receive a tax refund, a work bonus, a gift, or an inheritance? Resist the urge to splurge. Instead, allocate a significant portion, if not all, of these windfalls directly to your emergency fund. This can provide a substantial boost and help you reach your Emergency Fund 2026 target much faster.
Step 4: Tackle Debt Strategically
While the primary focus is building your emergency fund, managing debt, especially high-interest debt, runs parallel to this goal. Carrying significant credit card debt, for instance, can undermine the purpose of an emergency fund, as the interest payments can be crippling.
Prioritize High-Interest Debt
Many financial experts recommend a two-pronged approach: save a small starter emergency fund (e.g., $1,000-$2,000) first, then aggressively pay down high-interest debt, and then focus on fully funding your emergency fund. The reason is simple: the interest you save by paying off high-interest debt often outweighs the interest you’d earn in a savings account.
Once you have your starter fund, direct any extra money towards credit cards or personal loans with high interest rates. Once those are cleared, you can then pivot back to fully funding your Emergency Fund 2026.
Avoid Taking on New Debt
As you build your emergency fund, make a conscious effort to avoid taking on any new debt, especially for non-essential purchases. If an unexpected expense arises, use your nascent emergency fund rather than reaching for a credit card. This reinforces the purpose of your fund and keeps you on track for your Emergency Fund 2026 goal.
Step 5: Monitor, Adjust, and Stay Motivated
Building an Emergency Fund 2026 is not a set-it-and-forget-it endeavor. It requires ongoing attention and occasional adjustments.
Regularly Review Your Progress
Set aside time once a month, or at least quarterly, to review your budget and check your emergency fund balance. Are you on track to meet your monthly saving goal? Is your overall progress aligning with your December 2026 target? Adjust your saving contributions or spending habits as needed.
Reassess Your Essential Expenses
Life changes. Your rent might increase, or your transportation costs might shift. Periodically reassess your essential monthly expenses to ensure your emergency fund target still accurately reflects your needs. If your expenses have increased significantly, you may need to slightly adjust your Emergency Fund 2026 target or accelerate your saving efforts.
Stay Motivated with Milestones
The journey to December 2026 can feel long. Break your overall goal into smaller milestones. Celebrate when you hit your first $1,000, then your first month’s expenses, then three months’ expenses. Acknowledge your progress to keep motivation high. Visual aids, like a savings tracker or a thermometer chart, can also be incredibly motivating.
Step 6: Where to Keep Your Emergency Fund
The location of your emergency fund is almost as important as its existence. It needs to strike a balance between accessibility and growth.
High-Yield Savings Accounts (HYSAs)
As mentioned, HYSAs are generally the best home for your emergency fund. They offer significantly higher interest rates than traditional savings accounts, meaning your money works harder for you. They are also FDIC-insured (up to $250,000 per depositor per institution), providing peace of mind. Most HYSAs allow for easy electronic transfers, ensuring your money is available when you need it, typically within 1-3 business days.
Money Market Accounts (MMAs)
Similar to HYSAs, MMAs often offer competitive interest rates and check-writing privileges. However, they may have higher minimum balance requirements and sometimes limit the number of transactions per month. Compare rates and terms to see if an MMA is a better fit for your Emergency Fund 2026.
Why Not to Invest Your Emergency Fund
While investing is crucial for long-term wealth building, your emergency fund should not be invested in volatile assets like stocks or mutual funds. The primary goal of this fund is safety and accessibility, not growth. If the market takes a downturn just when you need the money, you could be forced to sell at a loss, defeating the purpose of the fund.
Common Pitfalls to Avoid on Your Emergency Fund Journey
Even with the best intentions, building an emergency fund can present challenges. Being aware of common pitfalls can help you navigate them successfully.
Lifestyle Creep
As your income increases, it’s natural to want to enjoy the fruits of your labor. However, allowing your spending to increase proportionally with your income (lifestyle creep) can make it harder to save. Resist the urge to upgrade your lifestyle significantly until your Emergency Fund 2026 is fully funded and you’re consistently meeting other financial goals.
Dipping into the Fund for Non-Emergencies
This is a big one. It can be tempting to use your emergency fund for a great sale, a vacation, or a new gadget. Remember, this fund is for true emergencies. Every time you dip into it for a non-emergency, you set yourself back and prolong the time it takes to reach your December 2026 goal. Be disciplined and remind yourself of the purpose of this vital safety net.
Not Adjusting for Inflation or Life Changes
Over time, the cost of living tends to increase. While December 2026 isn’t far off, it’s good practice to periodically review your essential expenses to ensure your target fund amount remains adequate. If your family situation changes (e.g., new child, new responsibilities), your needs may also evolve, requiring an adjustment to your Emergency Fund 2026 target.
Procrastination
The biggest hurdle for many is simply getting started. The task can seem overwhelming. Break it down, start small, and remember that every dollar saved is a step in the right direction. The sooner you start, the easier it will be to reach your Emergency Fund 2026 goal.
Maintaining Your Emergency Fund Post-2026
Reaching your goal of six months’ living expenses by December 2026 is a monumental achievement. But the journey doesn’t end there. Maintaining your fund is just as important as building it.
Replenish After Use
If you have to use your emergency fund for a legitimate emergency, make replenishing it your top financial priority. Treat it like a debt you owe yourself, and redirect your savings efforts back to rebuilding the fund until it’s back to its full six-month capacity.
Annual Review and Adjustment
Once a year, perhaps around the start of a new year, conduct a thorough review of your emergency fund. Re-calculate your essential monthly expenses. Has anything changed significantly? Do you need more or less in your fund? Adjust accordingly to ensure your financial safety net remains robust and relevant to your current life circumstances.
Consider Long-Term Financial Goals
Once your emergency fund is fully funded and maintained, you can shift your aggressive saving strategies towards other long-term financial goals, such as retirement savings, a down payment on a home, or investing for wealth accumulation. Your fully funded Emergency Fund 2026 will provide a stable base from which to pursue these aspirations.
Conclusion: Your Path to Financial Resilience by December 2026
Building a robust emergency fund is one of the most empowering financial decisions you can make. By setting a clear goal – accumulating six months of living expenses by December 2026 – you’re giving yourself a powerful target and a defined timeline. This guide has provided you with the framework: calculate your needs, create a realistic plan, implement aggressive saving and income-boosting strategies, manage debt wisely, and continuously monitor your progress.
Remember, consistency is key. Small, consistent actions over time lead to significant results. Embrace the challenge, celebrate your milestones, and stay disciplined. By December 2026, you won’t just have a substantial emergency fund; you’ll have cultivated invaluable financial habits and achieved a profound sense of security and peace of mind. Start today, and make your Emergency Fund 2026 goal a reality.
Frequently Asked Questions About Emergency Funds
- Q: How quickly should I build my emergency fund?
- A: While our goal is December 2026, the speed depends on your individual financial situation. Some can do it in months, others in a few years. The most important thing is to start and be consistent, even if it’s a small amount each month.
- Q: Can I use my emergency fund for a down payment on a house?
- A: No, an emergency fund is strictly for unexpected emergencies. Using it for a down payment, while a financial goal, is not an emergency and would leave you vulnerable to unforeseen circumstances.
- Q: What if I have a lot of high-interest debt? Should I save or pay off debt first?
- A: A common strategy is to save a small starter emergency fund ($1,000-$2,000) first. This protects you from going further into debt for minor emergencies. Once that’s established, aggressively pay down high-interest debt. After that, focus on fully funding your emergency fund.
- Q: Where is the safest place to keep my emergency fund?
- A: A high-yield savings account (HYSA) at an FDIC-insured bank is generally the safest and most accessible option. Avoid investing it in the stock market due to volatility.
- Q: How often should I review my emergency fund amount?
- A: It’s a good idea to review your essential expenses and emergency fund target annually, or whenever there’s a significant change in your living situation or financial responsibilities.