Student Loan Repayment 2026: 3 Solutions to Cut Payments by 15%
Anúncios
The Latest on Student Loan Repayment in 2026: 3 Practical Solutions to Reduce Your Monthly Payments by 15%
For millions of Americans, the burden of student loan debt is a pervasive concern that shapes financial decisions, career paths, and even life milestones. As we look ahead to 2026, understanding the evolving landscape of student loan repayment is more crucial than ever. With economic shifts, potential policy changes, and the ongoing need for financial stability, borrowers are continually seeking effective strategies to manage and reduce their monthly payments. This comprehensive guide will delve into the current state of student loan repayment in 2026 and, more importantly, equip you with three practical solutions designed to help you reduce your monthly payments by a significant 15% or more. Whether you’re just starting your repayment journey, grappling with existing debt, or looking to optimize your financial strategy, these insights will provide a clear roadmap to a more manageable financial future.
The sheer volume of student loan debt in the United States is staggering, impacting a diverse demographic from recent graduates to seasoned professionals. The average borrower faces a substantial monthly payment, which can often feel overwhelming. However, it’s not a situation without remedies. Proactive steps and a solid understanding of available options can make a considerable difference. Our focus today is on empowering you with actionable strategies for student loan repayment that are both realistic and impactful. We’ll explore how income-driven repayment plans can offer a safety net, how refinancing can unlock lower interest rates, and how loan consolidation can simplify and potentially reduce your overall burden.
Anúncios
Before diving into the solutions, it’s important to acknowledge the context of 2026. While specific policy changes are always subject to legislative processes, the general trend points towards a continued emphasis on borrower support and flexibility. However, relying solely on government intervention isn’t a sustainable long-term strategy. Personal financial planning and leveraging existing programs are key. By the end of this article, you will have a comprehensive understanding of how to approach your student loan repayment with confidence, armed with the knowledge to potentially save hundreds, if not thousands, of dollars annually.
Understanding the 2026 Student Loan Landscape
The landscape of student loan repayment is dynamic, influenced by economic indicators, federal policies, and the individual circumstances of borrowers. In 2026, we anticipate a continued focus on accessible repayment options, but also a growing expectation for borrowers to actively engage with their loan servicers and understand their rights and responsibilities. The federal government has, in recent years, introduced and expanded programs designed to alleviate financial stress, but these often require proactive enrollment and regular re-evaluation.
Anúncios
One of the persistent challenges for borrowers is navigating the complexity of different loan types—federal versus private—and the myriad of repayment plans available. Federal student loans typically offer more robust protections and flexible repayment options, while private loans are often subject to market interest rates and stricter terms. Understanding which type of loans you hold is the first critical step in devising an effective student loan repayment strategy.
Furthermore, the economic climate in 2026 plays a significant role. Inflation rates, employment figures, and interest rate trends can all impact a borrower’s ability to make payments. A robust economy might mean more job opportunities and higher wages, making payments more manageable. Conversely, an economic downturn could necessitate a deeper dive into relief programs. Staying informed about these broader economic trends, even if indirectly, can help you anticipate potential challenges and opportunities in your student loan repayment journey.
Another factor to consider is the potential for new legislation or adjustments to existing programs. While we cannot predict the future with certainty, advocacy groups and policymakers continuously work towards improving the student loan system. This means that options available today might be refined or expanded tomorrow. Regularly checking official government resources and reputable financial news outlets for updates is a good practice for any borrower committed to optimizing their student loan repayment plan.
In summary, approaching student loan repayment in 2026 requires more than just making monthly payments. It demands an informed, proactive, and adaptive mindset. The solutions we are about to explore are grounded in the current realities of the financial landscape and are designed to offer tangible relief.
Solution 1: Harnessing Income-Driven Repayment (IDR) Plans
One of the most powerful tools available for federal student loan repayment is the suite of Income-Driven Repayment (IDR) plans. These plans are specifically designed to make monthly loan payments affordable by capping them at a percentage of your discretionary income. For many borrowers, especially those with lower incomes relative to their debt, IDRs can significantly reduce monthly obligations, sometimes even to $0. Our goal here is to show you how IDR plans can help you achieve that 15% reduction, or even more.
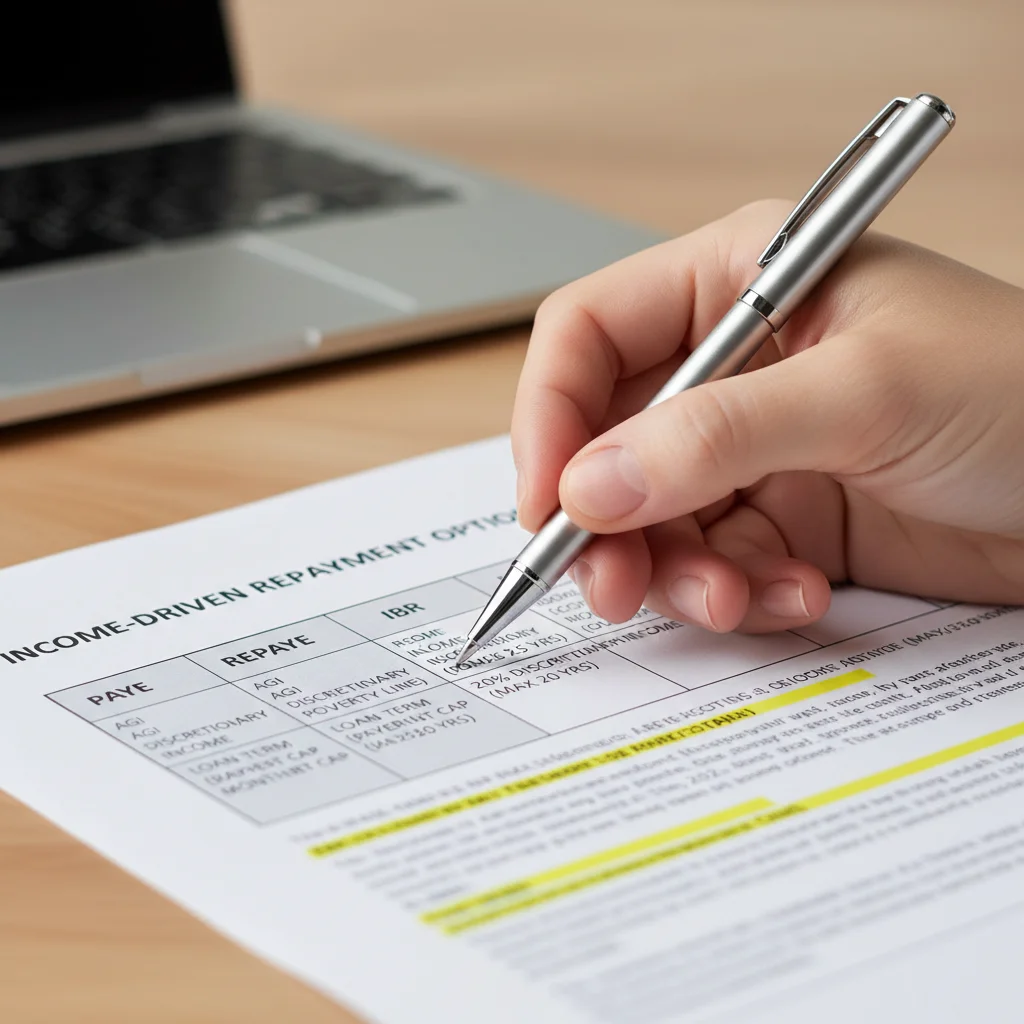
There are several types of IDR plans, including Income-Based Repayment (IBR), Pay As You Earn (PAYE), Revised Pay As You Earn (REPAYE), and Income-Contingent Repayment (ICR). Each plan has slightly different eligibility requirements and payment calculation methodologies, but they all share the core principle of adjusting your payment based on your income and family size. This means that as your financial situation changes, your payments can change too, offering a crucial safety net.
To qualify for most IDR plans, your federal student loan payments under a standard 10-year plan must be a high percentage of your income. The payment cap typically ranges from 10% to 20% of your discretionary income. For example, under the REPAYE plan, your monthly payment is generally 10% of your discretionary income. Discretionary income is usually defined as the difference between your adjusted gross income (AGI) and 150% of the poverty guideline for your family size and state of residence.
Let’s consider an example: If your standard payment is $400 per month, but under an IDR plan, your payment is calculated at $300, you’ve already achieved a 25% reduction. Even if your income is higher, an IDR plan can still offer a noticeable decrease. The key is to understand your specific financial situation, compare the different IDR plans, and choose the one that offers the most favorable terms for you. You must reapply for IDR plans annually, providing updated income and family size information. This annual certification ensures your payments remain aligned with your current financial capacity.
Beyond lower monthly payments, IDR plans offer another significant benefit: loan forgiveness. After 20 or 25 years of qualifying payments (depending on the plan and when you took out your loans), any remaining balance on your federal student loans will be forgiven. While this might seem like a distant future, it provides a valuable long-term incentive and reassurance. Moreover, for those working in public service, the Public Service Loan Forgiveness (PSLF) program can forgive remaining balances after just 10 years of qualifying payments under an IDR plan.
To effectively utilize an IDR plan for your student loan repayment, follow these steps:
- Identify Your Federal Loans: Confirm which of your loans are federal and eligible for IDR plans. Private loans are not eligible.
- Gather Financial Documents: You’ll need your most recent tax return (or pay stubs if your income has significantly changed) and information about your family size.
- Use the Loan Simulator: The Federal Student Aid website offers a ‘Loan Simulator’ tool that allows you to compare different IDR plans and estimate your monthly payments under each. This is an invaluable resource for finding the optimal plan.
- Apply Online: You can apply for or change your IDR plan directly on the Federal Student Aid website or through your loan servicer.
- Recertify Annually: Remember to recertify your income and family size each year to ensure your payments remain accurate and you stay enrolled in the plan.
Solution 2: Exploring Student Loan Refinancing
For many borrowers, particularly those with private student loans or federal loans with high interest rates, refinancing can be a game-changer in their student loan repayment strategy. Refinancing involves taking out a new loan with a private lender to pay off one or more existing student loans. The primary goal is to secure a lower interest rate, which in turn reduces your monthly payment and the total amount of interest you’ll pay over the life of the loan. Achieving a 15% reduction in monthly payments through refinancing is often quite feasible, especially if your credit score has improved since you first took out your loans.
The eligibility for refinancing largely depends on your creditworthiness. Lenders will evaluate your credit score, income, and debt-to-income ratio. A strong credit history, stable employment, and a healthy income are key factors that can help you qualify for the most competitive interest rates. If your credit score has improved significantly since you originally took out your loans, or if you have a co-signer with excellent credit, refinancing could offer substantial savings.
One of the most attractive aspects of refinancing is the ability to choose a new loan term. You can opt for a shorter term to pay off your loans faster and save on total interest, or a longer term to reduce your monthly payments. For the purpose of reducing your monthly payments by 15%, choosing a slightly longer term with a lower interest rate is a common and effective strategy. However, be mindful that a longer term, while reducing monthly payments, may increase the total interest paid over the life of the loan if the interest rate isn’t significantly lower.
It’s crucial to understand the distinction between refinancing federal and private loans. While refinancing private loans generally carries little downside, refinancing federal loans requires careful consideration. When you refinance federal student loans with a private lender, you lose access to valuable federal benefits such as income-driven repayment plans, generous deferment and forbearance options, and potential loan forgiveness programs like PSLF. Therefore, if you have federal loans, weigh the benefits of a lower interest rate against the loss of these protections. For borrowers with stable employment and a solid emergency fund, the trade-off might be worthwhile, but for those who anticipate needing flexibility, retaining federal loan benefits could be more important.
To effectively explore refinancing for your student loan repayment, consider these steps:
- Check Your Credit Score: Obtain your credit report and score. A higher score (generally 670+ for good, 740+ for very good, 800+ for excellent) will open doors to better rates.
- Compare Lenders: Research multiple private lenders. Many offer pre-qualification processes that allow you to see potential rates without impacting your credit score. Look for lenders with competitive rates, flexible terms, and positive customer reviews.
- Calculate Potential Savings: Use online refinancing calculators to estimate how much you could save on your monthly payments and overall interest. This will help you determine if a 15% reduction is achievable.
- Understand the Terms: Carefully review the loan terms, including fixed vs. variable interest rates, fees, and repayment schedules. Fixed rates offer predictability, while variable rates can start lower but may increase over time.
- Apply: Once you’ve chosen a lender and a loan product that aligns with your financial goals, complete the application process. This typically involves providing income verification, loan statements, and personal identification.
Refinancing is a powerful tool for those with good credit who are confident in their financial stability. By strategically leveraging lower interest rates and optimized loan terms, you can significantly lighten your monthly student loan repayment burden.
Solution 3: Strategizing with Loan Consolidation
Loan consolidation is another vital strategy in managing student loan repayment, particularly for borrowers juggling multiple federal student loans. While often confused with refinancing, consolidation is distinct: it combines several federal loans into a single new federal loan, simplifying your payments and potentially lowering your monthly obligation by extending your repayment period. This approach can certainly contribute to achieving a 15% reduction in your monthly payments, primarily through an extended term.
The Direct Consolidation Loan program, offered by the U.S. Department of Education, allows you to combine various federal education loans into one. The new consolidated loan will have a single interest rate, which is a weighted average of the interest rates of the loans being consolidated, rounded up to the nearest one-eighth of a percentage point. Crucially, consolidation does not typically lower your interest rate; its main benefits are simplification and the ability to access new repayment plans.
One of the key advantages of consolidation for student loan repayment is the ability to extend your repayment term up to 30 years. By stretching out the repayment period, your monthly payments will decrease, making them more manageable. For example, if you have a $50,000 loan balance with a 10-year repayment term, your monthly payment might be around $500. Consolidating and extending that to a 20-year term could reduce your payment to approximately $330, a reduction of over 30%. While this extends the total time you’re in debt and may increase the total interest paid over the life of the loan, it provides immediate relief to your monthly budget.
Furthermore, consolidating your federal loans can open doors to certain income-driven repayment plans or Public Service Loan Forgiveness (PSLF) that some older federal loans might not have been eligible for. For instance, if you have Federal Family Education Loan (FFEL) Program loans, consolidating them into a Direct Consolidation Loan can make them eligible for PSLF and more flexible IDR plans. This is a significant consideration for borrowers aiming for forgiveness programs.
However, there are important considerations when pursuing consolidation. If you consolidate loans that are already on an income-driven repayment plan, any progress you’ve made towards loan forgiveness on those original loans will reset. This is a critical point to understand, especially for those close to achieving forgiveness. Always check with your loan servicer and use the Federal Student Aid website’s resources to understand the implications for your specific situation.
To effectively use loan consolidation as part of your student loan repayment strategy:
- Identify Eligible Loans: Confirm that all the loans you wish to consolidate are federal student loans.
- Assess Your Repayment Goals: Are you looking primarily for lower monthly payments, simplification, or access to specific repayment or forgiveness programs?
- Understand the Interest Rate: Remember that consolidation typically doesn’t lower your interest rate; it averages your existing rates.
- Consider the Forgiveness Reset: If you are already on an IDR plan and have made significant progress towards forgiveness, carefully weigh the pros and cons of resetting that clock.
- Apply for a Direct Consolidation Loan: You can apply online through the Federal Student Aid website. The application process will guide you through selecting the loans you want to consolidate and choosing a repayment plan for your new consolidated loan.
Comparing the Solutions: Which is Right for Your Student Loan Repayment?
Now that we’ve explored three distinct strategies for managing your student loan repayment in 2026, it’s essential to understand when each solution is most appropriate. There isn’t a one-size-fits-all answer, as the best approach depends heavily on your individual financial situation, loan types, and long-term goals.
Income-Driven Repayment (IDR) Plans:
- Best For: Federal student loan borrowers with a high debt-to-income ratio, those experiencing financial hardship, or individuals pursuing Public Service Loan Forgiveness (PSLF). It’s also ideal if you anticipate your income fluctuating.
- Pros: Payments based on income and family size (can be as low as $0), potential for loan forgiveness after 20-25 years (or 10 years for PSLF), and protection against default.
- Cons: Interest can accrue, potentially increasing the total amount repaid over time if your payments are low. Annual recertification is required. The forgiven amount might be taxed as income (with some exceptions like PSLF).
- Impact on 15% Reduction: Highly effective, often achieving more than a 15% reduction for eligible borrowers.
Student Loan Refinancing:
- Best For: Borrowers with excellent credit (or a co-signer with excellent credit) and stable income, particularly those with high-interest private loans. Also suitable for federal loan borrowers who are confident they won’t need federal protections like IDR or forgiveness.
- Pros: Potentially lower interest rates (fixed or variable), reduced monthly payments, ability to choose a new loan term, and simplification of payments if you combine multiple loans.
- Cons: Loss of federal loan benefits (IDR, deferment, forbearance, forgiveness) if federal loans are refinanced. Requires a good credit score to qualify for the best rates.
- Impact on 15% Reduction: Very effective, often achieving a 15% or greater reduction, especially with improved credit or a lower interest rate environment.
Loan Consolidation (Federal Direct Consolidation Loan):
- Best For: Federal student loan borrowers who want to simplify multiple payments into one, gain access to IDR plans or PSLF for previously ineligible loans, or extend their repayment term to lower monthly payments.
- Pros: Single monthly payment, extended repayment term (up to 30 years) which lowers monthly payments, and eligibility for certain federal repayment plans/forgiveness programs.
- Cons: Does not lower your interest rate (it’s a weighted average). Can reset the clock on progress towards IDR forgiveness. Total interest paid may increase due to a longer repayment term.
- Impact on 15% Reduction: Effective for reducing monthly payments by extending the term, easily achieving a 15% reduction, but potentially at the cost of higher total interest over time.
It’s also worth noting that these strategies are not always mutually exclusive. For instance, you might consolidate your federal loans to access a specific IDR plan, or you might refinance your private loans while keeping your federal loans on an IDR plan. A hybrid approach can often yield the best results for comprehensive student loan repayment management.
Beyond the Three Solutions: Additional Tips for Student Loan Repayment in 2026
While IDR plans, refinancing, and consolidation are powerful tools, a holistic approach to student loan repayment involves several other best practices. Incorporating these tips can further enhance your financial stability and accelerate your path to debt freedom.
1. Budgeting and Financial Planning:
At the core of effective debt management is a solid budget. Understanding exactly where your money goes each month allows you to identify areas for savings that can be redirected towards your student loans. Even small additional payments can significantly reduce the total interest paid and shorten your repayment term. Tools like budgeting apps, spreadsheets, or even simple pen and paper can help you track your income and expenses meticulously.
2. Emergency Fund:
Before making extra payments, ensure you have an adequate emergency fund (typically 3-6 months of living expenses). This financial cushion prevents you from falling back into debt or missing loan payments if unexpected expenses arise, thus protecting your credit score and your student loan repayment progress.
3. Employer Assistance Programs:
Some employers offer student loan assistance programs as part of their benefits package. These can range from direct contributions to your loan principal to financial wellness coaching. Inquire with your HR department about any such benefits that could aid your student loan repayment efforts.
4. Explore Deferment and Forbearance (as a last resort):
If you face severe financial hardship and cannot make your payments, federal loans offer options like deferment and forbearance. These temporarily pause your payments. However, interest often continues to accrue during these periods, which can increase your total loan balance. Use these options only when absolutely necessary and understand their implications for your long-term student loan repayment plan.
5. Understand Your Loan Servicer:
Your loan servicer is your primary point of contact for all things related to your loans. Understand who they are, how to contact them, and what services they offer. They can provide detailed information about your loans, explain repayment options, and guide you through application processes. Don’t hesitate to reach out to them if you have questions or need assistance with your student loan repayment.
6. Automate Payments:
Setting up automatic payments can help you avoid missed payments, which can incur late fees and negatively impact your credit score. Many servicers also offer a small interest rate reduction (e.g., 0.25%) for enrolling in auto-pay, providing a small but consistent saving on your student loan repayment.
7. Consider the Avalanche or Snowball Method for Extra Payments:
If you have extra funds to put towards your loans, consider debt repayment strategies like the avalanche method (paying off the loan with the highest interest rate first) or the snowball method (paying off the smallest balance first). The avalanche method saves you the most money on interest, while the snowball method provides psychological wins that can keep you motivated.
Conclusion: Taking Control of Your Student Loan Repayment in 2026
Navigating student loan repayment in 2026 doesn’t have to be a daunting task. By understanding the current landscape and proactively implementing the right strategies, you can significantly reduce your monthly payments and gain greater control over your financial future. We’ve explored three powerful solutions: leveraging Income-Driven Repayment plans for federal loans, strategically refinancing for lower interest rates (especially for private loans), and utilizing federal loan consolidation for simplified payments and extended terms.
Achieving a 15% reduction in your monthly payments is not only feasible but often an achievable goal when you apply these methods diligently. Remember to assess your specific situation, compare the benefits and drawbacks of each option, and utilize the resources available to you, particularly the Federal Student Aid website and your loan servicer.
Beyond these core solutions, integrating sound financial practices such as budgeting, maintaining an emergency fund, and exploring employer assistance programs will further strengthen your position. The journey to financial freedom from student loan debt is a marathon, not a sprint. With informed decisions and consistent effort, you can transform your student loan repayment from a source of stress into a manageable part of your financial life, paving the way for a more secure and prosperous future.
Take the first step today: review your loan statements, visit the Federal Student Aid website, and start exploring which of these solutions can best serve your financial goals in 2026. Your future self will thank you.